


01 / The estimate

Not sure what to finance yet?
Get your ADU cost estimate first.
See a real Orange County ADU cost range on-screen in under a minute — then we'll structure the loan around a number you can trust.

Financing · Avorino
Orange County, CaliforniaConstruction financing in Orange County
Avorino works with construction-loan partners who underwrite for the project. Adjust the sliders to see a sample monthly during construction and after rollover to permanent debt.
Cost clarity
Real-time cost visibility starts before drawings. Avorino introduces you to construction-loan partners who underwrite against the same architectural set we'll build from — so the package the lender quotes is the package we'll actually deliver.
Sample borrowing widget
Avorino works with construction-loan partners who underwrite for the project. Adjust the sliders to see a sample monthly during construction and after rollover to permanent debt.
Sample numbers calibrated to current OC market — not a quote. Real terms come from the construction-loan partners we'll introduce you to.
What we structure (6)
Construction-to-perm, construction-only, owner-builder, bridge + lot, renovation, home-equity — Avorino routes you to the lender partner whose product fits your deal profile.

Single close. Construction draws during build, refinances to fixed-rate perm at Certificate of Occupancy. One closing, one fee schedule.
Two-close structure. Build with one lender, take out perm with another. Use when comparing perm rates matters.
When the owner runs the GC role. Limited cases, tighter underwriting, higher equity asks.
Funding the lot purchase + pre-construction soft costs (architect, engineer, soils, survey).
Reno-specific products that fund staged draws against renovation milestones. Different underwriting from purchase-money.
Borrow against the equity in your primary home — often the simplest route for an ADU when the equity is there. Keeps your first mortgage untouched.
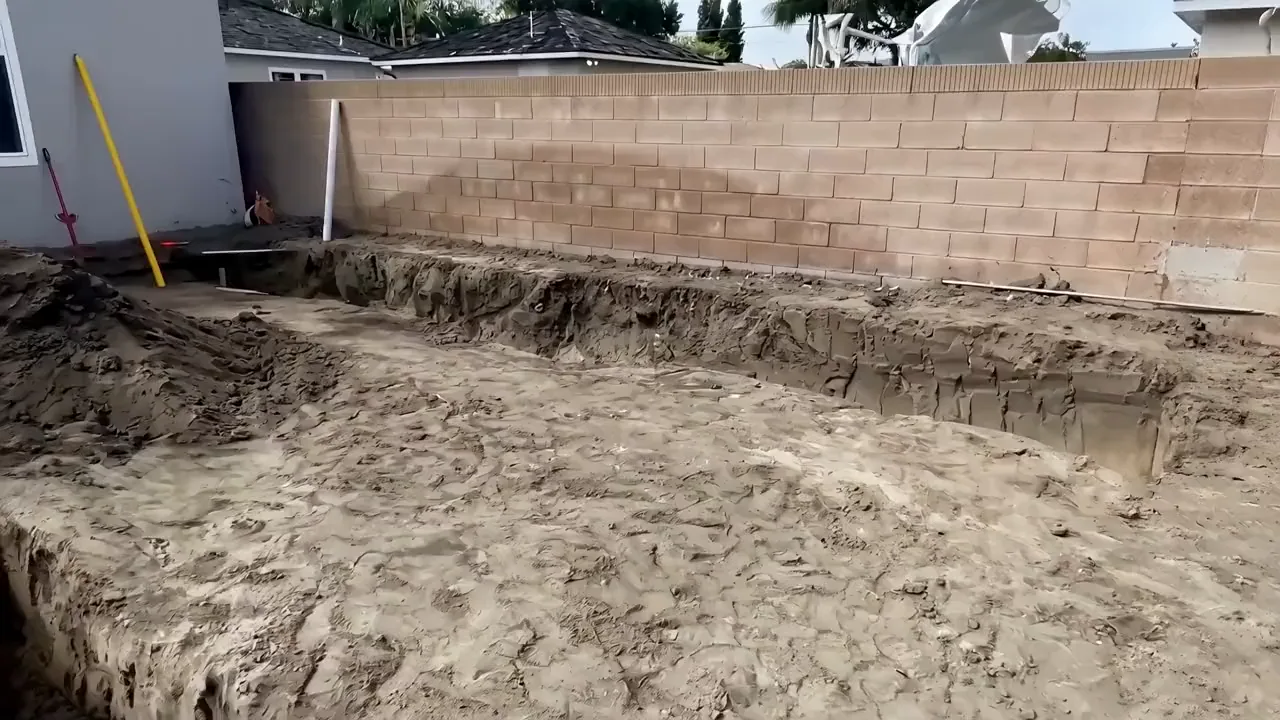
Designed and built by Avorino · Garden Grove
A time-lapse visualization of a detached ADU build in Garden Grove, from excavation to the finished exterior. Inspector visits each milestone; lender funds the draw; we keep building. Cycle repeats every 2–4+ weeks.
Process
Pre-qual, plans, underwriting, draws, refinance: the five steps of a construction loan, in order. From early project review to final approval and refinance — five phases.


01 / 05
We introduce you to construction-loan partners who fit your deal profile. They quote rates and terms; you pick.
02 / 05
Lender orders a plans-as-built appraisal off your architectural set. The number drives the loan-to-value math.
03 / 05
Income docs, asset statements, contractor agreements, draw schedule. Closing typically 30–60+ days from package.
04 / 05
Inspector visits each milestone; lender funds the draw; we keep building. Cycle repeats every 2–4+ weeks.
05 / 05
Certificate of occupancy lets the construction loan refinance to permanent debt (single-close) or pay off via separate perm (two-close).
Construction-phase rates typically run 7–9%, interest-only on the draw schedule; the rollover-to-perm rate depends on the final appraisal and the 30-year market when the project finishes. Most lenders look for 20–30% equity-in (lot value plus cash) against the total project cost. Closing typically takes 30–60+ days from package.
Talk about your dealBy the numbers
How Avorino closes your construction loan
NexWin Capital Corp.

Avorino routes most of our construction-loan referrals to NexWin Capital Corp. They place deals with lenders who underwrite the project, not just the borrower, and who handle ADU draws + construction-to-perm rollovers for OC builds. Talk to us first; if a NexWin Capital Corp. product looks like the right fit, we'll introduce you directly.
Construction-to-perm, two-close, owner-builder, lot, and ADU-specific products. Underwriting tuned to OC permitting cycles.
Explore loan options at NexWin Capital Corp.Not sure what to finance yet?
See a real Orange County ADU cost range on-screen in under a minute — then we'll structure the loan around a number you can trust.
ADU Loan Calculator
The ADU Loan Calculator shows the monthly payment, total interest, and total repaid on an ADU build, and compares a HELOC, a cash-out refinance, construction-to-permanent, and renovation loans by what each one is underwritten on. No email required.
Before you compare loans, know that the state grant route is not open: ADU grants in California covers the CalHFA ADU Grant Program, fully allocated since December 28, 2023 as of CalHFA’s last update (archived July 14, 2026).
For the loan options themselves, side by side: ADU financing options for 2026 walks through how to fund an ADU in California and what each route is underwritten on.
Funded projects
01 / 08
Construction-to-perm (one-close), two-close construction + permanent, ADU-specific products, owner-builder, and lot loans. We refer most clients to NexWin Capital Corp.: their lending partners underwrite the project, not just the borrower.
We don't; that's the lender's job. We introduce you to two or three partners that match the project type and stay in the loop on draw schedules + appraisal coordination.
Construction-phase rates typically run 7–9% (interest-only on the draw schedule) and rollover-to-perm rates depend on the final appraisal + the prevailing 30-yr market when the project finishes.
Most lenders look for 20–30% equity-in (lot value + cash) against the total project cost. Owner-builder products can sometimes accept less.
Talk To Us
Tell us the build, the rough budget, and how you're hoping to finance it. We'll follow up as soon as possible with construction-loan partners that actually fit the deal — no shared lists.

Service areas